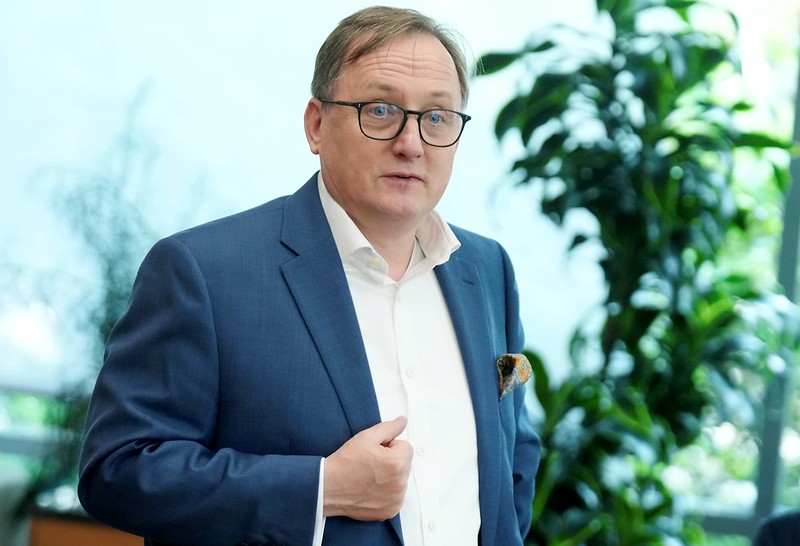
By David Barwick – FRANKFURT (Econostream) – The European Central Bank is likely to have further to go in tightening monetary policy if its September baseline holds, Governing Council member Mārtiņš Kazāks told Econostream, with policy rates ultimately needing to enter restrictive territory.
“If our baseline materializes, moving into restrictive territory will be necessary, but uncertainty is too high to say so definitively now,” Kazāks, who heads Latvijas Banka, said in an interview finalized late Thursday (transcript here).
Kazāks indicated that another increase was his central expectation rather than merely an upside-risk possibility.
“My personal view is that the case for further tightening is building up. The September 10th increase is unlikely to be our last move unless we find ourselves in a very different scenario than our baseline,” he said.
“The inflation threat is gradually building. Growth has surprised us on the upside, the economy is robust and labor markets remain strong. Our forecast expects the output gap to close in 2027.”
The strength of the economy comes alongside a deterioration in the nearer-term inflation picture, even as longer-term expectations remain contained.
“Medium- and long-term inflation expectations remain anchored, but short-term expectations have clearly risen, and inflation of 3.5% can’t be taken lightly,” Kazāks said.
The timing of the next move remains open, with Kazāks explicitly rejecting the notion that the ECB needs to wait for a meeting accompanied by new staff projections.
“Every meeting is live. Projection meetings allow for a richer analysis, but I would not segregate projection and non-projection meetings,” he said.
He nevertheless saw no immediate need to accelerate the pace absent a significant deterioration in the data.
“It is not possible to determine the timing now, but unless there is a sharp change in the data—for example, a big increase in energy prices—there is no rush to move again," he said. "An increase in October would still be consistent with the September projections.”
The ECB also retains flexibility over how far to move at any individual meeting, according to Kazāks, despite the gradual approach taken so far.
“We are not tied to a particular hike size. If the move in inflation is very strong or we see core inflation moving up, we can take bigger steps,” he said.
“If the world suddenly jumps from one state to another, we may need to jump as well.”
Under less extreme circumstances, however, Kazāks saw advantages in maintaining the step-by-step approach.
“In the past, we have done quite a good job of moving step by step while retaining full optionality, and that should continue,” he said. “There is always an element of ‘do no harm.’ Moving stepwise also allows us to remain flexible.”
“So far, the balance has been quite appropriate: there is no sense that we have done too little or too much. That allows us to remain relatively calm,” he said.
Nor does another rate increase depend on the ECB first finding evidence that the energy shock has spread decisively into wages and broader price-setting, Kazāks said.
“Second-round effects are not necessary. It is reassuring that they are not visible yet, but we should not wait for them to emerge,” he said.
“If they did become visible, that would be a very clear signal that rates would need to rise,” he said.
The ECB has so far found little evidence of such behavior, although Kazāks said both corporate pricing and wage-setting would have to be watched closely.
“So far, we have not seen significant repricing by companies or significant shifts in wage-setting, but both must be monitored closely,” he said.
The risk could increase as economic slack disappears, allowing the initial energy-driven rise in headline inflation to spread more easily, he said.
“As the output gap closes, there is a risk of headline inflation pulling core inflation higher. Companies may find it easier to pass through price increases,” Kazāks said.
“If inflation rises significantly above 3%, households may also become more sensitive to it," he said. "Inflation is much lower than it was in 2022, so the risk of nonlinear effects is also lower. But if inflation rises and we become increasingly concerned, we will act.”
Kazāks pointed to several possible explanations for the absence of significant second-round effects so far, including the smaller energy-price increase compared with earlier shocks and the credibility created by the ECB’s previous actions.
“We demonstrated in much more difficult circumstances that we were prepared to act, and we have already raised rates twice this year, showing that we are resolute,” he said.
“One important difference from the past is that there has been less fiscal support for demand, partly because fiscal space is more limited," he said. "The economy may also have become less energy-intensive and more reliant on renewables.”
Even a resolution of the Middle East conflict would not necessarily reverse the inflation consequences sufficiently to make additional tightening unnecessary, Kazāks said.
“No. A resolution of the conflict would not in itself remove the need for more tightening," he said. "The inflationary effects could still prove persistent.”
He pointed in particular to damage to energy infrastructure and pressures extending beyond the disruption to shipments through the Strait of Hormuz.
“Damaged infrastructure takes time to repair, and the problem is not just disruptions of shipments through the Strait of Hormuz," he said. "Some of the most striking developments have been in diesel spreads, which are up sharply, and our forecast does not assume that they will return to prewar levels,” he said.
“This partly reflects impaired refineries, not only in the Middle East but also in Russia,” he added.
Other channels could prolong the effects of the conflict even with food inflation having recently been weaker than expected, he said.
“Food inflation has been weaker than expected, but shipping remains severely disrupted," he said. "Wheat exports remain vulnerable to military action, which could add to food inflation. The heating season is also beginning.”
The tightening in financial conditions already delivered by higher long-term bond yields also does not obviate further action by the ECB, he said.
“It has produced some tightening, of course, but by no means enough to remove the need for policy action,” Kazāks said.
Higher yields could eventually have an additional disinflationary effect if they constrained fiscal spending, but Kazāks suggested that channel would operate only with a lag.
“If higher yields affect fiscal spending next year, lower expenditure would mean less demand and less inflationary pressure," he said. "But the rise in yields is relatively recent, and it takes time for the effects on fiscal spending to feed through.”
The degree to which recent economic resilience reflects fiscal stimulus rather than underlying private-sector strength remains uncertain, including in Germany, Kazāks said.
“Some estimates suggest that fiscal support accounts for nearly two thirds of Q2 growth in Germany. The support is tilted toward defense, however, which is less inflationary because defense goods are not part of households’ consumption basket,” he said.
“The German data were much stronger than expected, and some of that was due to fiscal support," he said. "The question is how that affects the coming quarters. The PMIs were also much better.”
He nevertheless saw stronger activity as increasing the ECB’s room to act.
“Irish data are always volatile, but stronger economic activity generally makes it easier to raise rates,” he said.
The ECB’s September inflation path should meanwhile not be read as showing what would happen if interest rates remained unchanged at their current level, because its technical assumptions already embody expectations of additional tightening, he said.
“The baseline projection is conditioned on market pricing, which incorporates some further tightening,” Kazāks said.
That distinction could help explain why financial markets and the ECB can share an understanding of the central bank’s reaction function while reaching different conclusions about the likely rate path, he said.
“Markets do understand our reaction function quite well. They expected us to move and we did, so our respective views were quite similar,” he said.
“But the market’s baseline may differ from ours," he said. Investors may, for example, be more optimistic about energy prices declining, or have a different assessment of the robustness and resilience of the European economy, especially Germany’s.”
“They may therefore understand the reaction function while applying it to a different baseline," he added.
Kazāks put the current 2.50% deposit rate at the top of the neutral range, but rejected treating that level as a constraint on additional tightening.
“In my view, however, 2.50% is the upper end of the neutral range, but it is not a magic barrier,” he said.
“I sometimes see comments suggesting that it would be hard for us to go beyond it—if necessary, we will move into restrictive territory. I would call 2.75% becoming restrictive,” he said.
The exchange rate, by contrast, was not currently an important source of concern, he said.
“Only the usual attention,” Kazāks said when asked how much attention the Council was paying to the euro exchange rate.
“Exchange rate movements take considerable time to feed through to inflation, and the euro has moved within a relatively narrow range in recent quarters," he said. "In my view, it is not currently a major driver of inflation risk.”
- The author of this story can be contacted at david.barwick@econostream-media.com
END