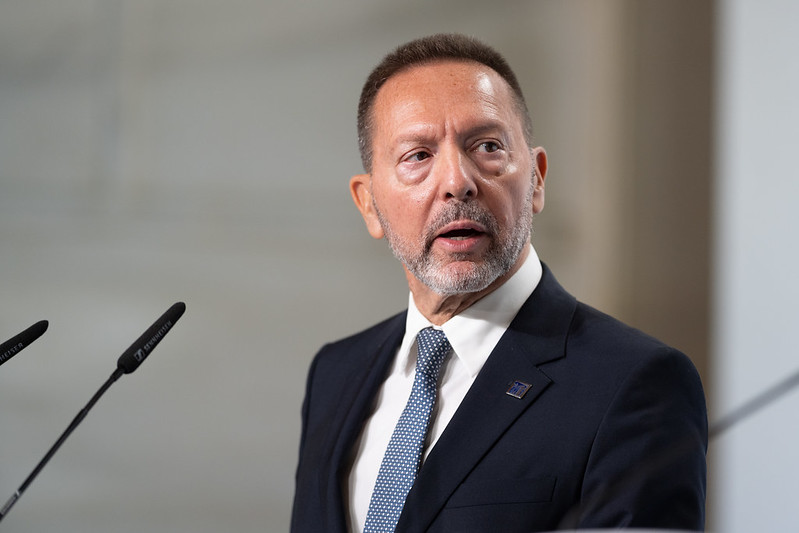
By David Barwick – FRANKFURT (Econostream) – Eurosystem instruments must remain flexible and supported by credit assessments that go beyond reliance on external ratings, while national governments must address fiscal and structural weaknesses, European Central Bank Governing Council member Yannis Stournaras said late Monday.
In a speech in Buenos Aires at the invitation of the Central Bank of Argentina, Stournaras, who heads the Bank of Greece, said Greece’s recovery demonstrated the importance of combining credible domestic policies with effective European institutions.
“Eurosystem instruments need to be flexible, supported by sound risk controls and credit assessments that go beyond mechanical reliance on external ratings,” he said.
Such arrangements helped prevent financial disruption from undermining domestic adjustment and supported predictable financing conditions for investment, while allowing borrowing costs to reflect differences in credit risk, he said.
“The European lesson is that a common currency must be supported by credible national policies and effective common institutions,” he said.
Euro area membership had provided Greece with a reliable monetary anchor but had neither prevented fiscal and external imbalances nor ensured that capital reached its most productive uses, Stournaras said. Sovereign stress and financial distress had subsequently disrupted monetary policy transmission, limiting the support that monetary easing could provide, he said.
Stournaras highlighted the ECB’s collateral waiver for Greek government securities during the adjustment programs and the inclusion of Greek bonds in the Pandemic Emergency Purchase Programme before the country regained investment-grade status.
“More broadly, the PEPP’s flexibility in allocating purchases across countries helped prevent tensions in individual sovereign debt markets from disrupting the transmission of the single monetary policy across the euro area,” he said.
European official lending on favorable terms had given Greece time to adjust, while implementation of domestic reform commitments had been essential to restoring confidence and sustainable market access, he said.
Greece’s debt-to-GDP ratio was projected to remain on a broadly downward trajectory under both the baseline and all adverse scenarios considered, including weaker primary balances, slower growth and higher financing costs, he said.
“With a weighted average maturity of around 18 years and fully fixed-rate exposure after hedging, increases in market rates feed through only gradually to debt-servicing costs,” he said.
Nevertheless, Greece’s external deficit remained a vulnerability, reflecting heavy import dependence and insufficient domestic saving alongside imports associated with recovering investment, Stournaras said. A lasting correction required stronger saving and productive investment that expanded exports and supported competitive import substitution, he said.
He also cautioned that repairing banks’ balance sheets did not resolve the economy’s entire distressed-debt burden. Between 2016 and 2026, banks’ non-performing loans had fallen by around 94%, but total non-performing private-sector debt had declined by only around 30%, he said.
“Transferring a loan changes the creditor, but does not, by itself, reduce the borrower’s debt burden or restore their capacity to invest,” he said.
Efficient courts, capable loan servicers and workable restructuring arrangements were therefore necessary to turn financial-sector repair into broader economic gains, he said.
Greece’s recovery rested on stronger foundations, but productivity and real incomes still bore the scars of the crisis, Stournaras said. Population aging would increasingly constrain growth, reinforcing the need for investment, productivity improvements and higher labor force participation, he said.
“Continued reforms and productive investment remain essential to translate these stronger foundations into lasting productivity gains and higher real incomes,” he said.