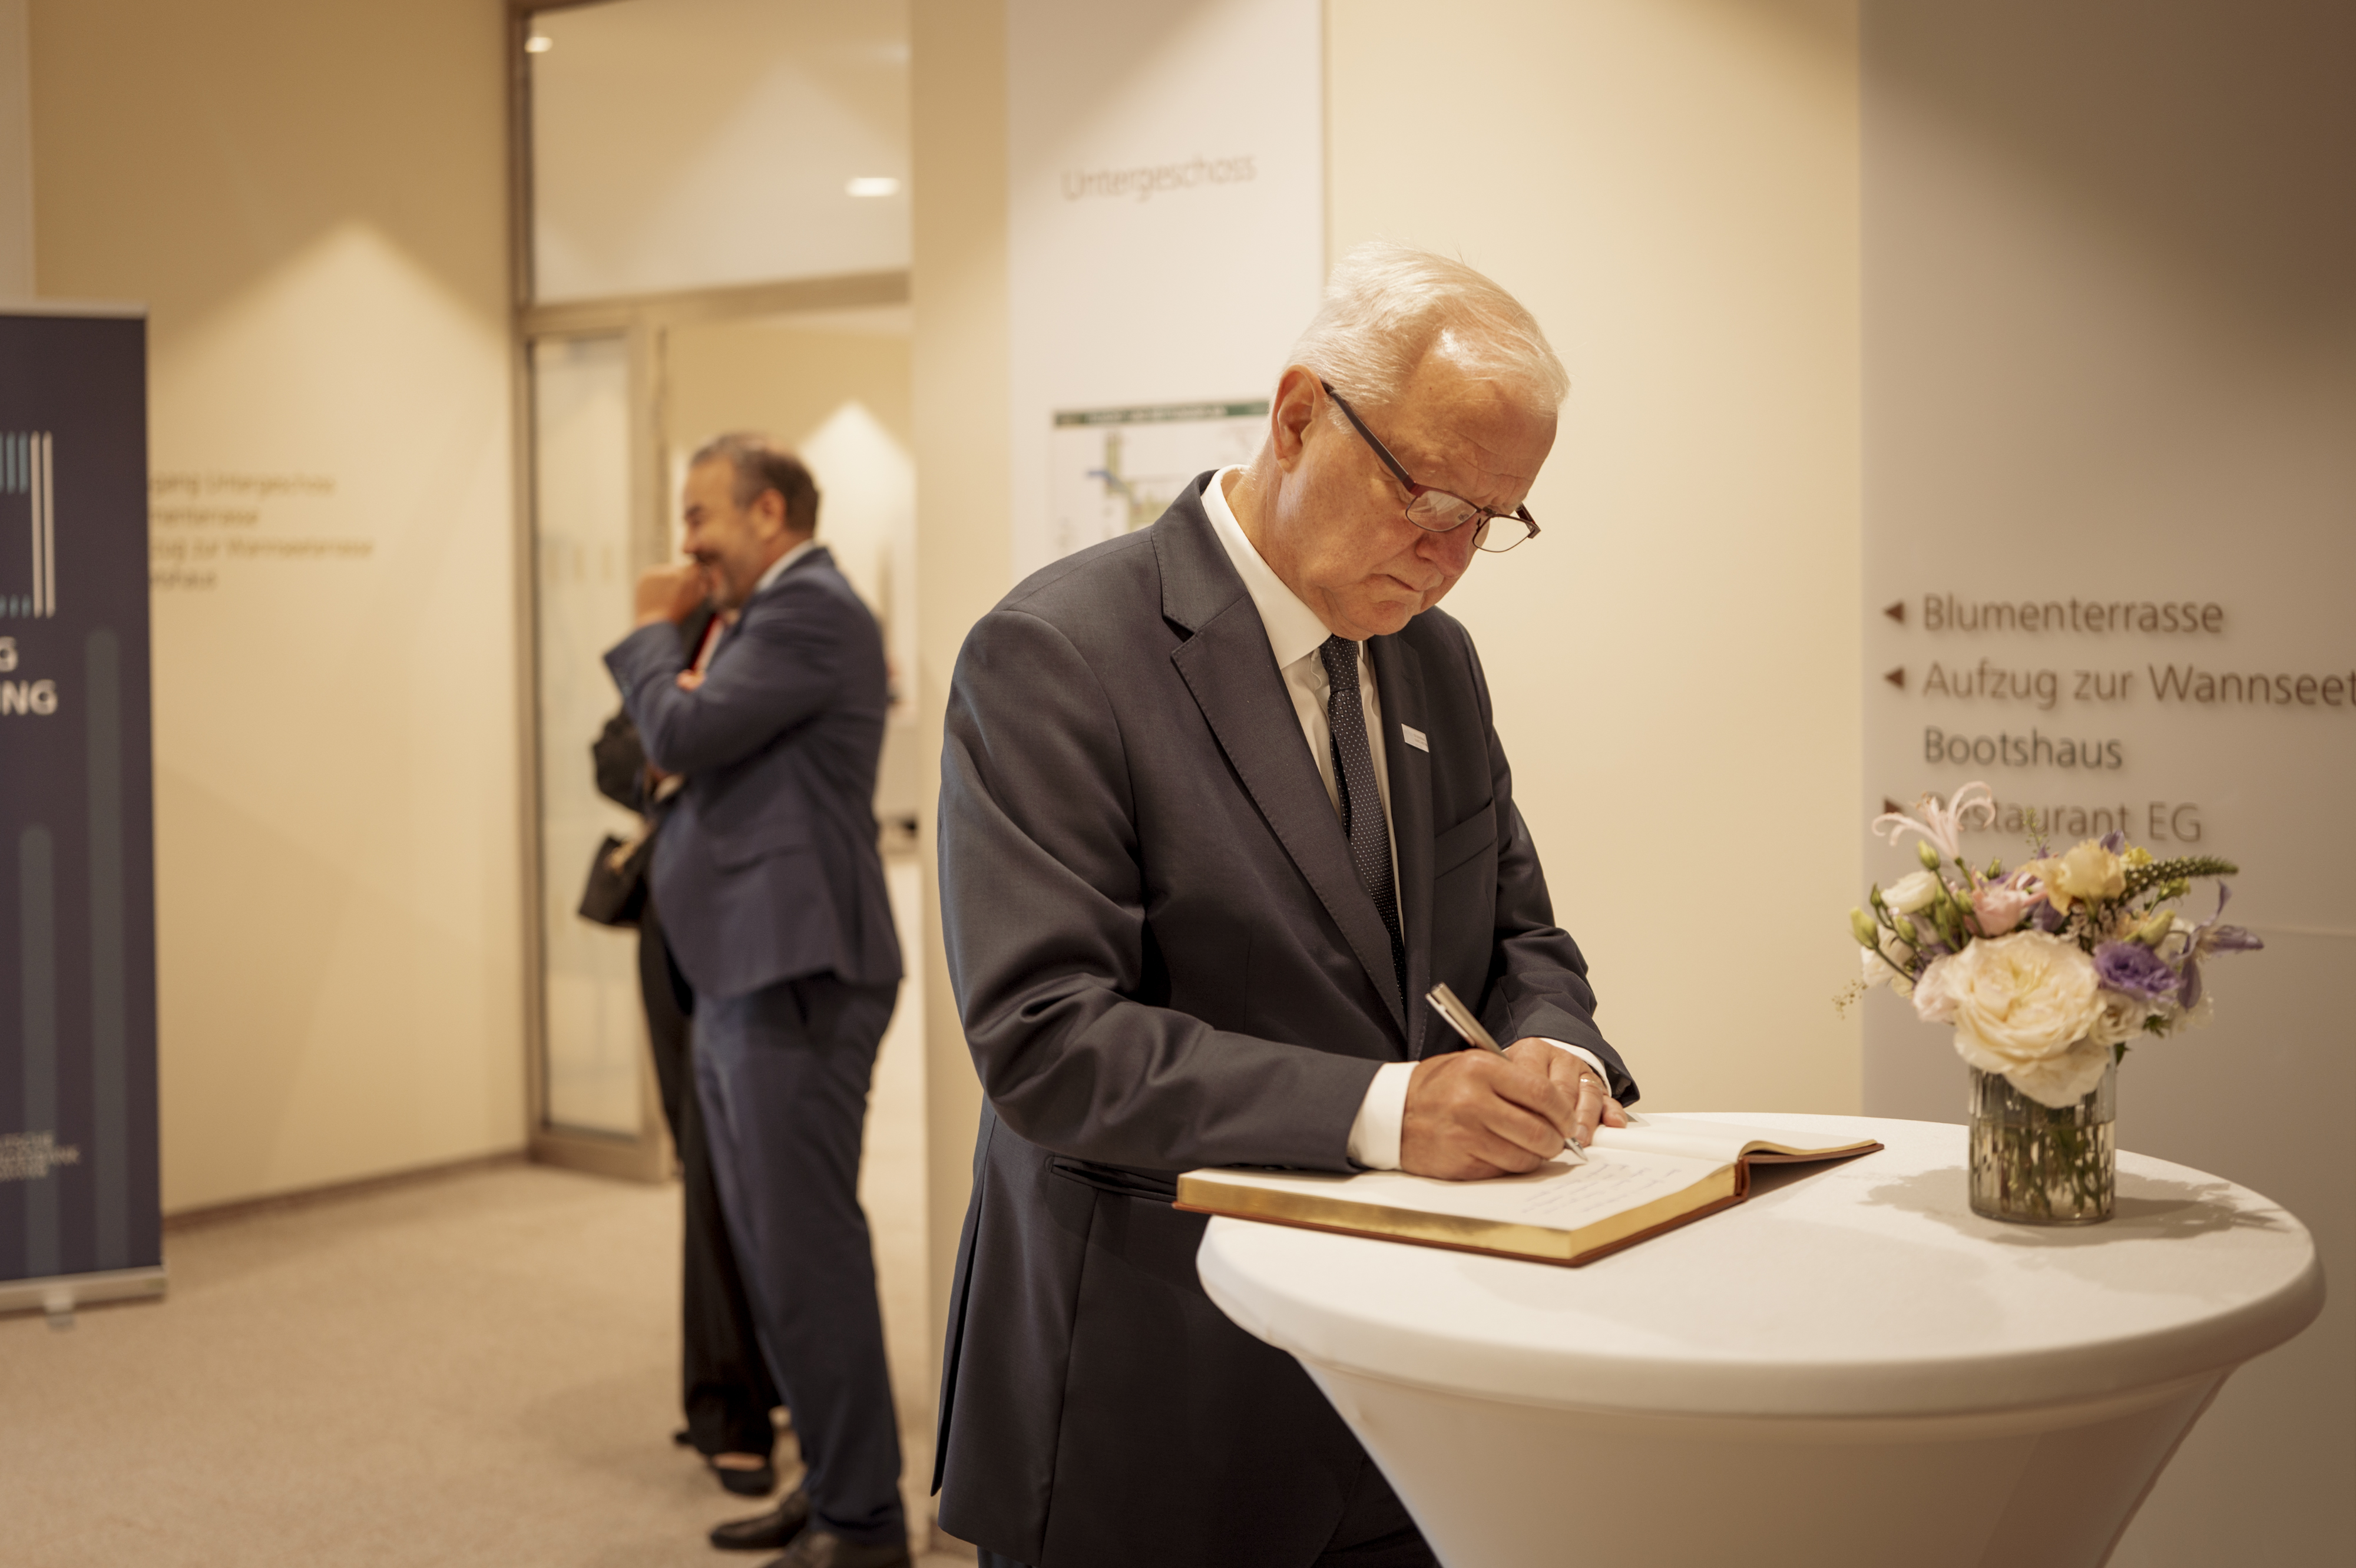
By Marta Vilar – MADRID (Econostream) – European Central Bank Governing Council member Olli Rehn said on Thursday that there was no evidence so far of second-round inflation effects in the Eurozone, but warned that policymakers could not be certain they would not emerge and needed to remain alert to signs that price pressures were broadening.
“We have to balance different considerations,” Rehn, who heads the Bank of Finland, said during a Q&A session following a speech in London.
“It is also one lesson that we learned from the previous crisis in the sense that it is not always easy to identify and you cannot always be fully certain that there are not indirect effects or second-round effects, so you have to be very mindful that they don’t start creeping in,” he said.
At the same time, headline inflation in the Eurozone had been above the ECB’s 2% target for some time, Rehn said.
Rehn said the Eurozone labor market was currently less tight than during the previous inflation shock, distinguishing the present environment from that following the Covid-19 pandemic and Russia’s invasion of Ukraine.
“The context of 2022 [...] and today are very different,” he said, pointing to the substantial monetary and fiscal stimulus still supporting the economy when the war began and the subsequent surge in inflation to above 10%.
At that time, “we saw inflation broadening, kind of creeping in, and then we started to see some second-round effects,” Rehn said.
Rehn said the ECB would continue to assess a broad set of indicators rather than make decisions on the basis of any single measure, with wage growth, inflation broadening and potential second-round effects particularly important.
The ECB followed wage growth and forward-looking wage indicators closely, particularly those that have proved reliable, such as its wage tracker, he said.
Financial conditions were another important consideration and had tightened recently, according to Rehn.
He defended the ECB’s decision last week to raise interest rates by 25bp despite the latest inflation pressures stemming largely from an energy supply shock.
With inflation currently above 3% and pressures from energy markets having strengthened, “in my view the decision in September was the right one,” Rehn said.
Rehn also stressed the high degree of uncertainty surrounding the outlook, pointing to recent swings in energy prices and cautioning against placing too much emphasis on where the economy currently sits relative to the ECB’s alternative scenarios.
“What I say today may be outdated tomorrow or in one week,” Rehn said.
On the monetary policy stance, Rehn said estimates of the neutral rate remained an important analytical framework but were of limited practical use in setting policy.
Related articles:
- ECB’s Rehn: Inflation Risks May Be Creeping Up, No Clear Broadening Yet
- ECB's Rehn Says Forward Guidance Should Remain In Toolkit, But Avoid Rigid Commitments
- The author of this story can be contacted at marta.vilar@econostream-media.com