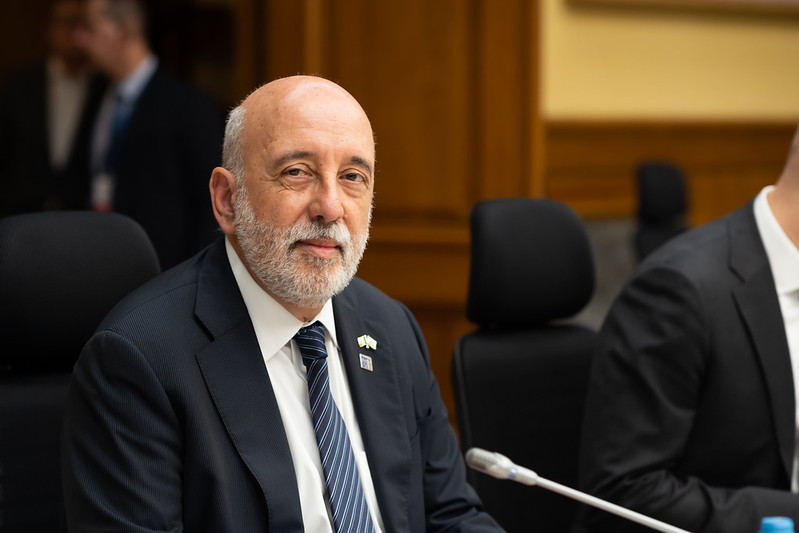
By David Barwick – FRANKFURT (Econostream) – The European Central Bank must be prepared to raise interest rates further, including into restrictive territory, if inflation risks shift significantly upward, ECB Governing Council member Gabriel Makhlouf told the Financial Times in an interview published Wednesday.
Makhlouf, who heads the Central Bank of Ireland, said that even after a widely expected 25bp increase next week to take the deposit rate to 2.5%, monetary policy would still not be restrictive.
“Policy is not restrictive,” Makhlouf said, adding that restrictive territory would begin, roughly speaking, only once rates moved above 2.75%.
The ECB should be prepared to move into that territory in the event of a significant upward shift in inflation risks, he said. If inflation began developing in the wrong direction, monetary policy would have to respond accordingly, he cautioned.
For now, however, Makhlouf said it was not clear that another increase would be necessary after next week's expected move, and backed retaining the ECB's meeting-by-meeting approach without forward guidance.
Makhlouf said next week's decision would not surprise anyone and expected the ECB to raise its 2026 euro area growth forecast slightly from the 0.8% projected in June.
He said he felt “uneasy” about euro area inflation remaining above 3% while economic growth was proving somewhat stronger than forecasters had expected before the summer.
The stronger growth performance was one factor making next week's rate decision “really clear cut,” Makhlouf said. Were inflation at 3.3% against a very subdued growth backdrop, the case for raising rates would be more complicated, he said.
Makhlouf said the better-than-expected growth performance was “not a fluke,” pointing to investment in artificial intelligence and defence as factors supporting activity.
At the same time, he pointed to evidence limiting the case for assuming that inflation pressures would necessarily require a succession of further increases. Inflation expectations remained well anchored, he said, while there was no evidence of second-round inflation effects through wages and the relevant risks were being managed.