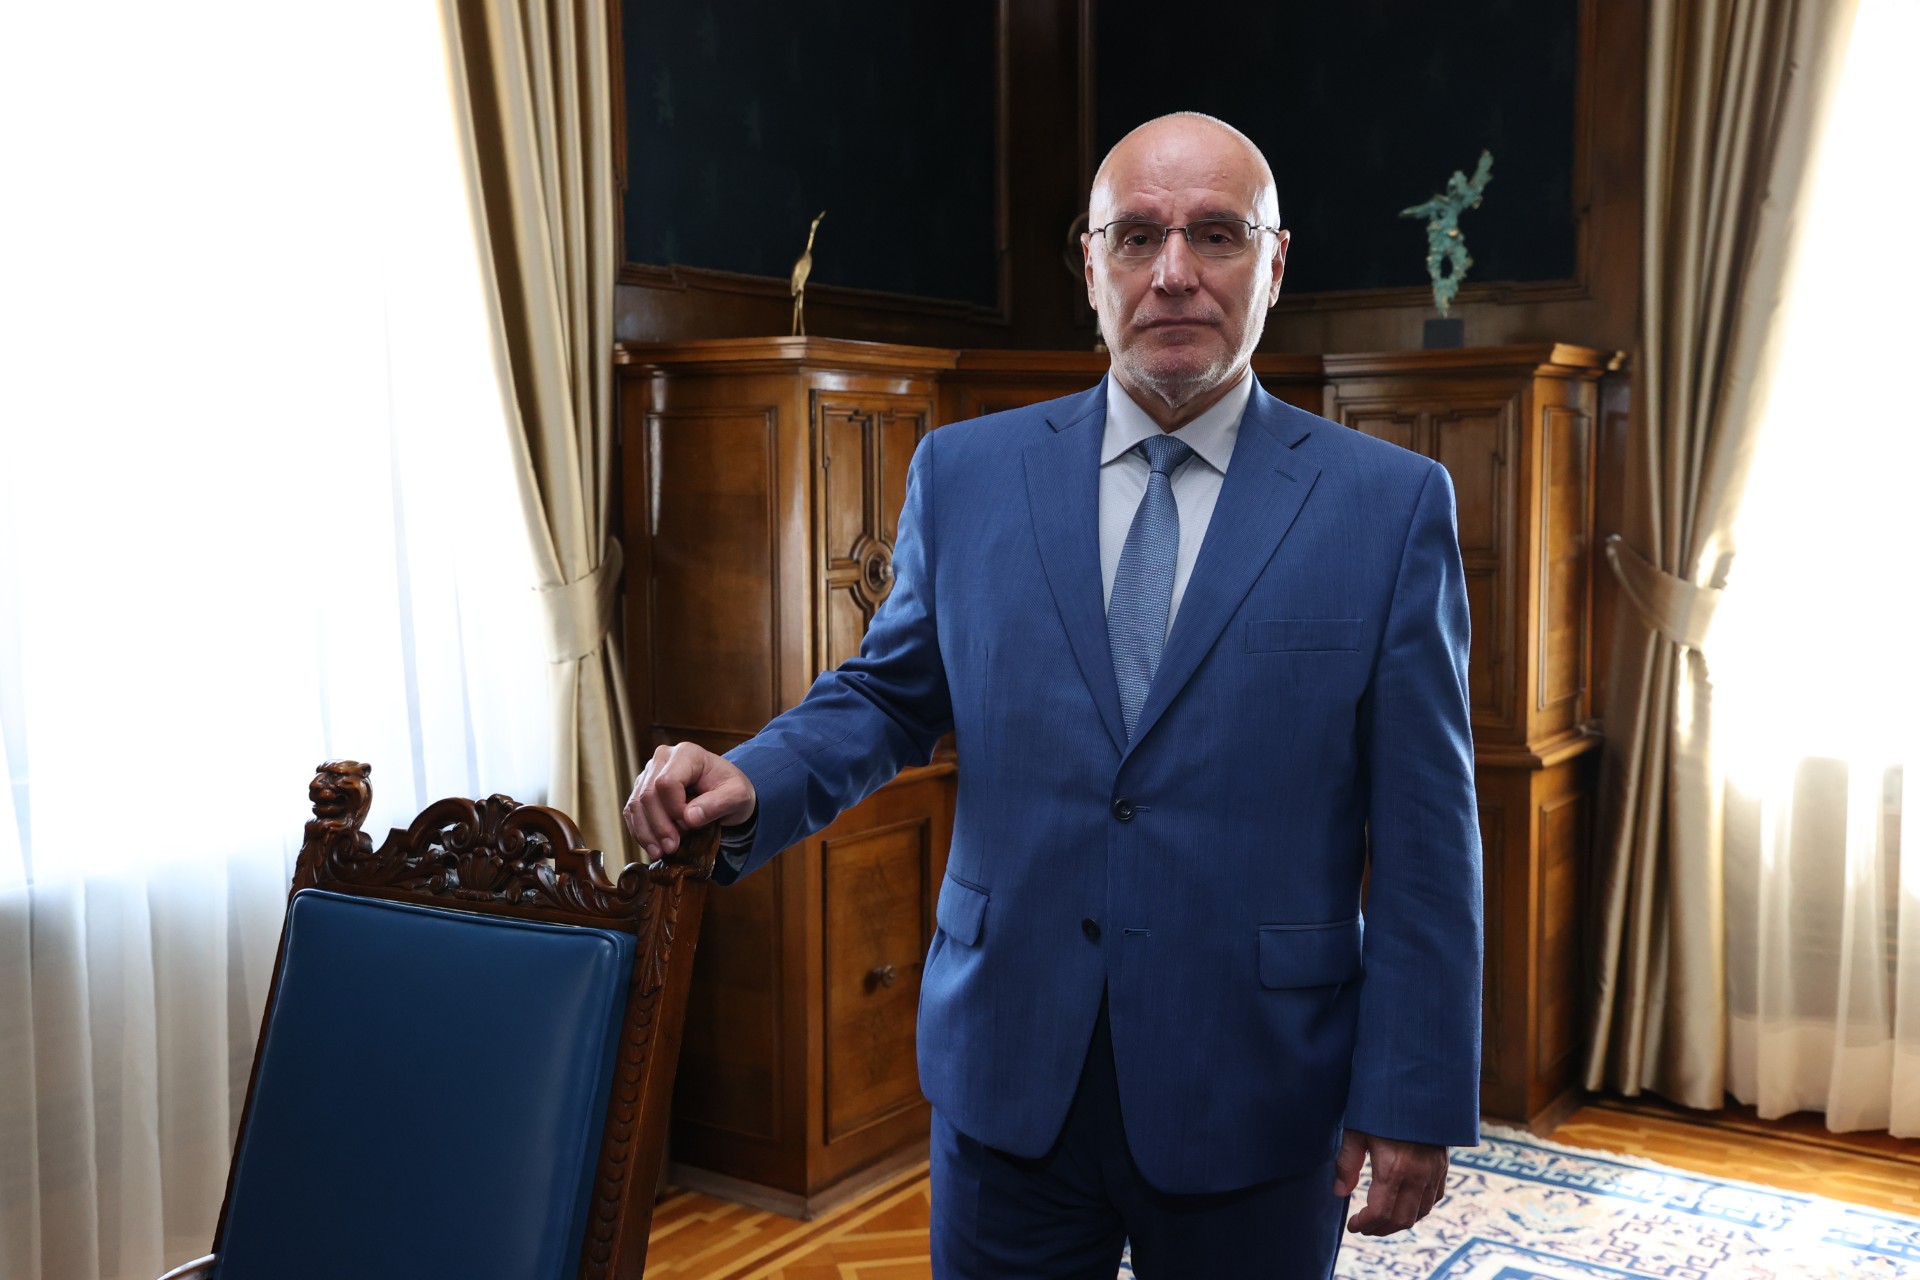
By Marta Vilar – SOFIA (Econostream) – Under current circumstances, prudence argues for the European Central Bank to “put more emphasis on vigilance” than patience after its September decision and communicate its readiness to act again, according to ECB Governing Council member Dimitar Radev.
In an interview with Econostream on 26 August 2026 (transcript here), Radev, who heads the Bulgarian National Bank, noted that the September decision was no foregone conclusion, but argued that available information increasingly supported the case for another rate hike.
“September remains open, but based on what we know today, another measured step deserves serious consideration,” he said, citing above-target inflation and the possibility that the energy shock could prove more persistent than initially expected.
Asked what could yet lead the ECB to hold rates steady in September, he stressed the need to closely monitor energy markets and financial conditions, both of which he said could change quickly.
“For example, clear evidence that energy price pressures are fading, broader inflation pressures remain contained, or monetary policy transmission is stronger than expected, would affect the balance,” he said. “The opposite developments would strengthen the case for action.”
On how the September decision should be communicated, Radev said the ECB should strike the right balance between patience and vigilance. While acknowledging that patience was “important,” he said that “vigilance should receive slightly more emphasis.”
The ECB should give its past interest rate hikes time to work through the economy, he added, but said that at the same time, “it should be very clear that we remain ready to act.”
“I think it’s also important to emphasize that patience in this case does not mean passivity,” he added.
With respect to the updated projections to be unveiled in September, Radev said he expected some upward pressure on near-term inflation, with economic growth likely to remain subdued.
Despite the economy having exhibited resilience so far, financial conditions were tightening, he said, and “in my view, the evidence is not yet sufficiently broad-based to conclude that the risks to growth are clearly to the upside.”
The Governing Council’s September decision would not predetermine subsequent steps, according to Radev, who nonetheless said he considered both the October and December meetings to be “live.”
Still, he rejected the idea of any default rate move after September and said the market-implied rate path embedded in the projections did not bind the Governing Council.
Asked about the recent rise in bond yields, Radev said the resulting tightening of financial conditions should be taken into account by the ECB.
Monetary policy in the euro area was not behind the curve, he said, but the danger was “to treat some persistent inflation signals as temporary without enough evidence.”
Although wage growth was moderating and there were no clear signs of second-round effects, Radev said a prolonged period of above-target inflation could affect wage negotiations, margins and price-setting behavior.
“Second-round effects could strengthen the case for action, but they’re not a precondition for the next move,” he said. “Waiting until second-round effects are fully visible could mean acting too late.”
Asked about various comments pointing to 2.5% as the new upper end of the neutral range, Radev said he would not treat that level “as a precise dividing line,” though it was “probably around the neutral range.”
He said he would “in principle” be willing to move into restrictive territory if conditions warranted it, even in the absence of visible second-round effects.
On recent speculation that he could be a candidate in the upcoming Bulgarian presidential election, Radev declined to comment but said he remained “focused on my work as Governor of the Bulgarian National Bank and a member of the Governing Council of the European Central Bank, and this is not going to change in the foreseeable future.”