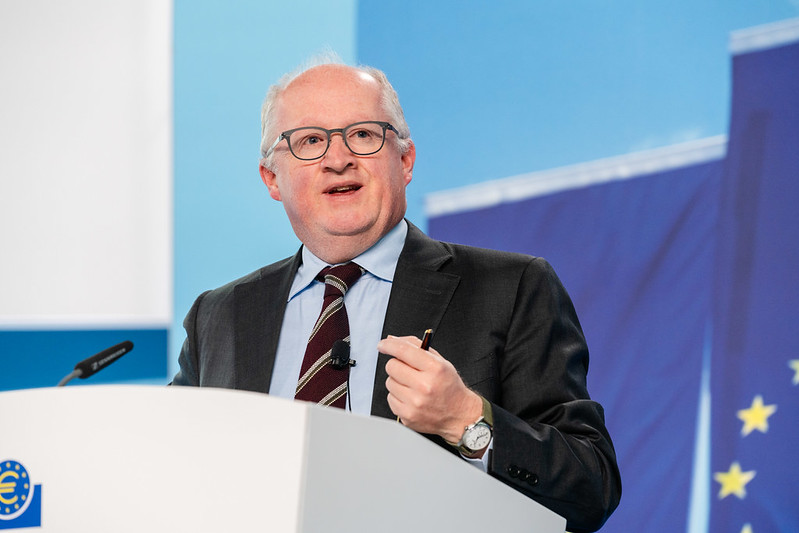
By David Barwick – FRANKFURT (Econostream) – European Central Bank Chief Economist Philip Lane on Tuesday pushed back against the idea that the ECB should refrain from raising interest rates because of the resulting burden on mortgage borrowers, saying tolerating excessively high inflation as a consequence would be a "false economy."
Asked in an interview on Irish radio station RTÉ Radio 1 whether he expected another interest rate increase by the end of the year, Lane declined to give a forecast, saying the ECB's decisions would depend on what was required to return inflation to its 2% target and on the strength of economic activity.
"What I would say is the rate decisions will be driven by what do we need to do to make sure inflation comes back to 2%. Side by side with that, a big influence on that is essentially how quickly is the economy growing," he said.
Lane said the European economy was currently doing "okayish," but cautioned that the relatively limited impact on the world economy so far from the war in the Middle East might not persist if the conflict remained unresolved.
"If we have an open-ended war in the Middle East with no resolution, the very benign impact on the world economy so far may change," he said. "So there's a lot of open questions."
Pressed on the importance of interest rates for millions of mortgage borrowers, Lane said the consequences of excessive inflation also had to be taken into account, particularly for lower-income households.
"What we found out from these years is inflation itself is so important, the cost of living crisis, inflation really affects people lower incomes more than higher incomes," he said.
"So essentially it's a false economy [...] to say, well, let's avoid rate increases because of the impact on mortgages if the cost of that is overall inflation remaining too high for too long."
Lane said inflation could hover around 3% for the rest of this year based on prevailing market assumptions, while stressing that the outlook depended heavily on energy prices and on whether the Middle East crisis was resolved.
"If you look at the market calculations I would say hovering around this 3% level is probably what people are looking at for the rest of this year," he said. "But that very much depends on whether there is a resolution to the crisis. It's really an uncertain situation."
He also said higher energy, fertilizer and other input costs would not automatically translate one-for-one into higher consumer prices because pass-through depended on the strength of demand.
"Those are all pressures on costs. But the connection between these cost pressures and overall prices do depend on the level of demand," Lane said.
"Essentially firms are essentially assessing, 'Can I pass through these price increases or do I have to absorb it in terms of lower profitability or scaling back activity levels?'" he said.
Lane said it was therefore necessary to consider the effect of large supply shocks on both inflation and economic activity.
"So it's important to always, in discussing these big shocks, side by side to look at the effect on inflation but also to look on the effect on demand, on activity levels," he said.
Food inflation, currently relatively low across Europe, was likely to become a more important source of price pressure over the next year, Lane said, with the effects of adverse weather conditions becoming most apparent in 2027.
"Our calculations would say this is going to be mostly in 2027," he said. "Already, the way the food production works has long lags. This is something that in summer 2027 will be most visible."
"We do think food inflation is going to be one of the drivers of overall inflation over the next year," he said.
Lane also identified artificial intelligence as another potentially important influence on the ECB's assessment of the economic outlook.
"One of the big issues for us and for everyone looking at it is the impact of AI on the world economy," he said. "We need to look at everything in a comprehensive manner."